 how-to
How to Trade In Your Car: A Step-by-Step Guide
Table of Contents
- Step 1: Gather the Documents Needed to Trade In a Car
- Step 2: Learn How to Prepare Your Car for Trade-In
- Step 3: Get Your Trade-In Appraised and Understand Market Value
- Step 4: Negotiate Your Trade-In Offer Like a Pro
- Step 5: Understand Trading in a Car with Negative Equity
- Step 6: Complete the Paperwork and Finalize Your Trade-In
- How to Trade In Your Car: Pros, Cons, and When to Walk Away
- Conclusion
- Frequently Asked Questions
Last Updated: September 22, 2026
Step 1: Gather the Documents Needed to Trade In a Car
The documents needed to trade in your car are your title or lien release, current registration, valid driver's license, loan payoff statement if you still owe money, and any service records you've kept. Dealers ask for all of these before they can legally take ownership.
Here's the full list to bring:
- Certificate of title (or lien release if you financed)
- Current registration and proof of insurance
- Valid driver's license for every name on the title
- Loan payoff letter from your lender, good for 10-14 days
- All keys, remotes, and floor mats
- Service records and a vehicle history report if you have one
Step 2: Learn How to Prepare Your Car for Trade-In
To prepare your car for trade-in, clean it inside and out, fix cheap cosmetic problems, gather your records, and skip expensive repairs. Dealers pay for condition and presentation, not perfection.
Then handle small, cheap fixes:
- Replace burned-out bulbs and worn wiper blades
- Top off fluids and check tire pressure
- Fix chips or cracks in the windshield if it's affordable
- Remove aftermarket decals and stickers
Step 3: Get Your Trade-In Appraised and Understand Market Value
A trade-in appraisal is a dealer's inspection and valuation of your car, based on its condition, mileage, and current market demand. The appraisal produces a trade-in allowance, which is what the dealer will credit toward your next car.
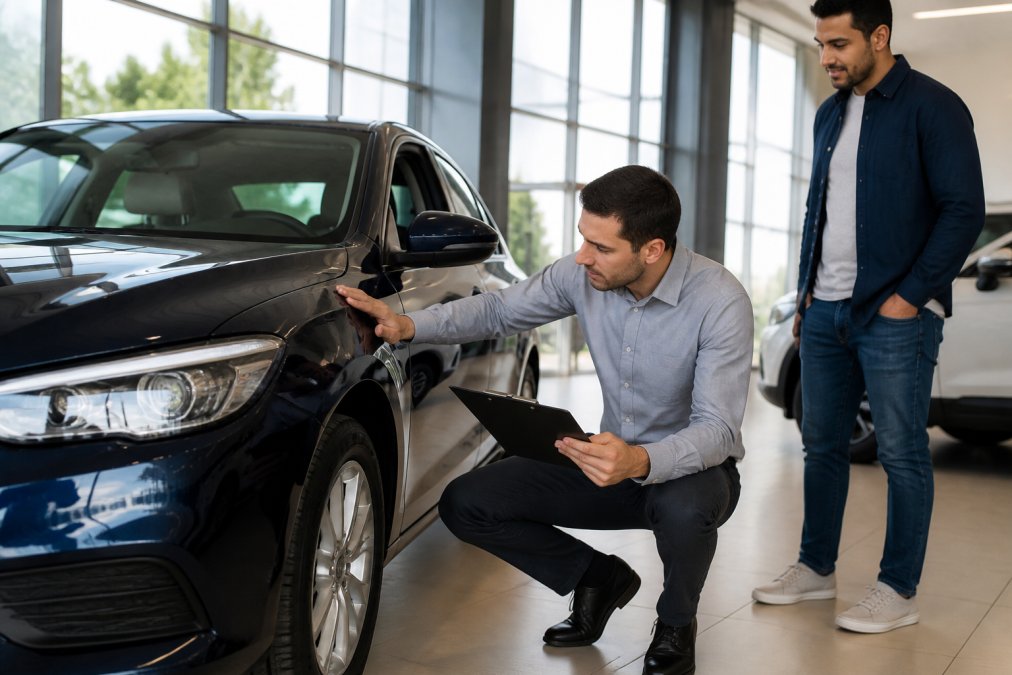
The appraiser will check:
- Odometer reading and overall mileage
- Vehicle condition report covering body, tires, and interior
- Vehicle identification number (VIN) to pull the vehicle history report
- Accident history, title status, and prior owners
Step 4: Negotiate Your Trade-In Offer Like a Pro
Negotiate your trade-in as a separate deal from the car you're buying. When you bundle them, the dealer can hide a low trade offer inside a "great" purchase price. Keep the two numbers apart, and settle the trade number first.
Why the dealer's first number is almost always low
A dealer's used-car operation has three numbers in mind: what they can sell your car for at retail, what they can get for it at wholesale auction, and what it costs them to recondition it. Their opening offer typically lands near wholesale minus reconditioning, with a built-in margin. That margin is the room you're negotiating against. Knowing this reframes the conversation: you're not asking for a favor, you're closing the gap between their opening number and a fair market number.
Red flags that signal a lowball or a stall
- "Let me talk to my manager" repeated three or more times. Sometimes real, often a pressure tactic to wear you down.
- The four-square worksheet. If the salesperson starts drawing a grid with trade, price, down payment, and monthly payment, they're blending the deals. Ask them to write the trade number on its own sheet.
- "We can't separate the trade from the purchase." They can. This is a scripted refusal.
- A trade number that swings wildly between visits. Appraisals should be consistent. Big swings mean they're pricing your patience, not your car.
- Pressure to sign anything before the trade number is agreed. Never sign a title or a purchase order with a blank trade line.
Scripts you can borrow
Opening anchor (after you've named your number):
"I've had this appraised at [your number] and I've seen similar cars listed for [retail range]. I'm looking for [target number] on the trade. If we can get there, I'll move forward today."
The psychology that actually moves the number
- Silence is a tool. After you name your price, stop talking. The first person to fill the silence usually concedes.
- Anchor high, but credibly. An anchor backed by comparable listings is respected. An anchor pulled from thin air gets dismissed.
- Never reveal urgency. If you mention a lease ending next week or a baby on the way, your leverage drops.
- Get at least two appraisals. A written offer from a second dealer is the single strongest negotiation asset you can carry in.
- Be willing to walk. The strongest move is meaning it. Dealers can tell the difference between a bluff and a decision.
Step 5: Understand Trading in a Car with Negative Equity
Trading in a car with negative equity means you owe more on your loan than the car is worth. You're "upside down." The gap doesn't disappear when you trade. It gets rolled into your next loan, and that changes the math on everything that follows.
The math, worked out
Say your car's trade-in offer is $14,000 and your lender's payoff quote is $18,500. The gap is $4,500. That $4,500 doesn't vanish. It gets added to the price of the car you're buying, which means you're financing the new car plus the old shortfall. On a 60-month loan at a typical used-car rate, that $4,500 alone can add roughly $80 to $95 to your monthly payment, and you'll pay interest on it for the full term.
Loan-to-value: the number lenders actually watch
Lenders cap how much they'll finance relative to a vehicle's value. A common ceiling is around 120% to 125% loan-to-value (LTV), though it varies by lender and credit profile. If your new loan would exceed that cap, the lender may require a larger down payment, a shorter term, or may decline the deal outright. This is why a large negative equity gap can stall a trade even when the dealer is willing.
Your realistic options
- Pay the difference in cash at the dealership. This keeps the new loan clean and avoids paying interest on the old shortfall.
- Roll the gap into the new loan. Convenient, but it raises your loan balance, your monthly payment, and your LTV. You may be upside down again the moment you drive off.
- Wait and pay down the loan. Every month you make a payment, the gap shrinks. If you can wait six to twelve months, the math often improves dramatically.
- Refinance first. If your credit score has improved since you bought, refinancing the existing loan at a lower rate can reduce the gap faster than paying it down alone.
- Sell privately instead. A private-party sale usually nets more than a trade-in, which can shrink or eliminate the gap.
What happens behind the scenes
When you trade a financed car, the dealer's finance office contacts your lien holder for a 10-day payoff quote. That quote includes the remaining principal plus any accrued interest and fees. The dealer pays the lien holder directly, the lien is released, and the title transfers to the dealer. If the payoff is more than the trade allowance, the difference is either collected from you or financed into the new deal.
Gap insurance and why it matters here
We work with buyers in this exact spot and walk through the math before anyone signs.
Step 6: Complete the Paperwork and Finalize Your Trade-In
Finalizing a trade-in means signing the title over, settling any loan, and completing a bill of sale. The dealer handles the title transfer and registration paperwork, and you get credit toward your new car.
What you'll sign:
- Title transfer and odometer disclosure
- Bill of sale listing the trade allowance
- Payoff authorization if a lien holder is involved
- New financing contracts for your next car
How to Trade In Your Car: Pros, Cons, and When to Walk Away
Trading in is fast and simple, but it usually pays less than a private party sale. Know the trade-offs before you decide.
| Factor | Trade-In | Private Sale |
|---|---|---|
| Payout | Lower (wholesale) | Higher (retail) |
| Speed | Same day | Weeks |
| Paperwork | Dealer handles it | You handle it |
| Tax credit | Often applies | Usually not |
| Risk | Low | Higher |
Conclusion
Trading in a car comes down to preparation and patience. Gather your documents, know your car's real value, and negotiate the trade as its own deal. That's how you protect your money.
Frequently Asked Questions
Is it financially smart to trade in your car?
Trading in usually nets less than a private party sale, but it saves time and reduces risk. You avoid listing, showing, and test-driving your car for strangers, and the dealer handles title transfer and paperwork. In most states, you also get a sales tax credit on the trade-in value, which offsets some of the difference. For anyone who values convenience or has a lien, trading in is often the smarter move.
How do you trade in a car that isn't paid off?
You can trade in a car with an outstanding loan. First, get your payoff amount from the lien holder. The dealer will appraise your car, then apply the trade-in value toward that payoff. If the offer is higher than the payoff, the difference goes toward your new vehicle or comes back to you. If it's lower, the remaining balance rolls into your new financing, which is negative equity.
Does cleaning your car increase trade-in value?
A thorough cleaning helps, but it won't transform a rough car into a top-dollar trade. Detailing, removing personal items, and fixing small cosmetic issues can nudge the appraisal up because the appraiser sees a well-maintained vehicle. Keep service records handy too. Major mechanical repairs rarely pay for themselves at trade-in, so skip expensive fixes unless they're safety-related.
What is the $3,000 rule for cars?
The $3,000 rule is a budgeting guideline that says if a repair costs more than roughly $3,000 or exceeds the car's value, it may be time to replace it rather than fix it. The number isn't a law, just a practical threshold. If you're facing a big repair bill on a high-mileage car, run the math on trade-in value versus repair cost before deciding to keep it.